Author: user

  • Contact Debtmerica Relief – We are here to help!

    Telephone:
    (800) 470-8155
    Mailing Address:
    Debtmerica, LLC
    Attn: Customer Care
    6 Hutton Centre Drive, Suite 200
    Santa Ana, CA 92707
    Business Hours:
    Monday – Friday: 7:00 AM – 7:00 PM PST
    Saturday: 9:00 AM – 2:00 PM PST

  • Debt Settlement Frequently Asked Questions

    Debt Settlement Frequently Asked Questions

    General Debt Settlement Questions

    Debtmerica’s 10 Questions to Ask a Debt Settlement Company

    AFCC’s Top 10 Frequently Asked Questions


    Can Debt Settlement Really Allow Me to Pay Back Less Than I Owe?

    If you are struggling to pay off your credit card debt, medical bills, or other unsecured debt, you may be wondering if the advertisements you see on the TV, radio or the Web are for real. The main questions consumers ask are “Can I really get out of debt for a fraction of the cost and pennies on the dollar? Will debt settlement help me get out of debt quickly, legally and safely? What are the effects on my credit rating and future ability to get a loan?

    Below you will see a variety of questions and answers that we wanted to share with you. These are among the most commonly asked. By reading on, it is our hope that you’ll be able to make an intelligent decision as to whether debt settlement is the right choice for you.

    What Is Debt Settlement?

    Debt Settlement (also referred to as debt negotiation, negotiated debt settlement or sometimes incorrectly called debt consolidation) means that your debt is negotiated down to a reduced amount and paid off in a lump sum. In some rare cases, multiple payments are utilized to pay off the debt, settling the account in full. In most cases, when you hear that debt can be paid off for pennies on the dollar, you are being misled. While in very rare cases, some debts can be settled for this very low figure, typically debts are settled within the range of about 15 – 75 cents on the dollar.

    Settlement is one of the most effective choices available to consumers. It’s a great choice if you have more debt than you can pay off in a 2 – 3 year time frame or are experiencing a financial hardship that has you falling behind (or just about to be) on your monthly payments. Why would creditors choose to settle debts rather than simply charge you interest and late fees over and over again? Well, it’s really a matter of dollars and good sense. Creditors know that if you get into such a bad financial position that you can’t pay your monthly payments, you may decide to declare bankruptcy or simply do nothing. In this case they may get nothing! Therefore, they are usually very willing to settle for a lower amount, given your hardship, than risk getting nothing at all, especially with a bankruptcy among the alternatives.

    Is Debt Settlement a Better Choice Than Bankruptcy?

    Bankruptcy may allow you to eliminate most of your debts quickly and this is typically referred to as a “Chapter 7 Bankruptcy.” In other cases, you may be required to pay back a percentage of your debts over time. This is typically referred to as a “Chapter 13 Bankruptcy.” Bankruptcy also offers legal protection under the court so that you don’t have to worry about being sued or harassed by creditors while completing the bankruptcy process. While most reputable debt settlement firms will work to assist in minimizing creditor calls and harassment where possible, debt settlement does not provide the guaranteed legal protection that bankruptcy does.

    Chapter 7 bankruptcy is not an option for everyone and it has gone through some changes since the bankruptcy reforms of 2005. Unlike the not so distant past, it has become more difficult to qualify for full liquidation (forgiveness) of your unsecured debts. Chapter 13 bankruptcy requires five years of court-ordered payments to a trustee, and may require you to surrender some of your assets.

    However, as getting all of your options will help you make a more informed decision, speaking to a bankruptcy attorney may be a worthwhile discussion. Most reputable debt settlement firms can refer you to a trusted bankruptcy attorney if you have detailed questions or if they determine that you might be better served by speaking to them instead. Typically, if you are in such a financial state of hardship that you can’t even make your minimum monthly payment into our program, speaking to a bankruptcy attorney is highly recommended.

    What Makes Me a Good Candidate for Debt Settlement?

    There are a few factors that a well-trained debt specialist can go over with you in more detail. In general, if you can afford to pay back your debts on your own by paying more than the minimum payment every month without hardship, it’s probably the best route. It will not impact your credit score (and may improve it), and it will likely be relatively pain free. For those in true (or soon to be) financial hardship, debt settlement from a trusted and time-tested organization is a better option. If your total unsecured debt balances are less than $10,000, Consumer Credit Counseling is an excellent choice as your payments can be consolidated into just one, and typically, interest rates are reduced on your accounts. However, be warned. Many counseling programs have a very high drop out rate, can last up to 5-7 years, and you end up paying back 100% of the debt you owe, plus any new interest.

    Where Can I Find A Trusted Debt Settlement Firm?

    With the huge rise in unemployment, unmanageable debt, economic problems, and uncertainty in the marketplace, many fly-by-night companies have sprouted up offering debt settlement to consumers that are not legitimate; in fact many are nothing more than scams. Some offer unrealistic settlement expectations or promise nearly impossible monthly payments and time horizons. They are simply doing this to make a quick buck at your expense!

    A good debt settlement firm always trains its agents to help you understand what your options are and is very realistic with you about what to expect. Often, companies simply looking to scam you look to collect fees up front regardless of whether they stand behind their promises.

    Be very careful! Many firms advertising an offer for debt settlement services are nothing more than lead generation firms that may sell your information to several potentially unscrupulous firms. Many of them will end up barraging you with constant phone calls and have nothing to do with the company you “thought” you were contacting. Make sure to clearly read and understand the privacy policy and terms of use of any firm that you call on or submit your information to.

    Will Debt Settlement Affect My Credit Score?

    If you are current on your payments, it is very difficult, if not impossible to settle your debt. Creditors typically want to see that you are in a hardship situation before they are willing to negotiate. Therefore, you will have to voluntarily stop paying your unsecured debts; allowing them go into delinquency before settlement. In addition, you cannot pick and choose which debts you wish to settle in most cases. Your creditors and/or collections agencies may review your credit report, and most will be unwilling to negotiate when they see that they are being offered less than what is owed to them while others are being paid on time as agreed. Secured debts, such as a home loan or car loan are collateralized; you should continue to pay these accounts on-time to avoid repossession or foreclosure proceedings.

    By not paying your creditors, your credit will be adversely affected by debt settlement. However, having to experience this circumstance may be better than having to file for bankruptcy, especially on your credit rating. During your debt settlement program, your total balances are being lowered over time as they are settled in full – a great start to recovery!

    Can I Settle My Debts On My Own?

    If you have just a couple debts or less than $10,000 in debt, you could to try to talk to your creditors directly to settle the accounts yourself. There is a lot of information publicly available to assist with this, but word to the wise: If you owe over $10,000 in debt, have several accounts you need to settle, or need the structure and the guidance of a knowledgeable professional, you should seek out the assistance of a knowledgeable debt settlement firm.

    Debt settlement is by no means an exact science. And it’s difficult for an individual lacking experience with creditors to determine whether a settlement is fair or not. In addition, you have to directly handle all creditor calls and the harassment that comes with the job. Many people are simply unable or uninterested in handling that kind of pressure, especially with the daily complexities of managing a job, household or family at the same time.

    Hiring a professional debt settlement firm with a good reputation can no doubt save you more money, give you better advice, and get you out of debt in a much less stressful manner, enabling you can move on with your life. Always make sure that you heavily screen who you are working with, and especially make sure that they are a fully accredited organization by a major industry association. AFCC (The American Fair Credit Council) is by far one of the most successful of these. Many if not most legitimate firms will at the very least be a member.

    How Will Debt Settlement Affect My Taxes?

    In general, in the United States, the IRS considers debt which is forgiven as income. This means if you borrow $15,000 on your credit cards and settle it for $8,000, the $7,000 difference is taxable as income since it is not repaid. However, the IRS will often waive this tax liability if you can show that you were insolvent during the time in which your debt settlement took place. We highly recommend a quick call to your accountant or tax professional for further discussion. You may be relieved with what they have to say!

    There are always very clear and real responsibilities when dealing with debt, especially when you don’t pay back 100% of what you owe. However, once you can remove your debt problem from your life, a whole new world of opportunity can open up for you.

    Debtmerica’s Ten Questions to Ask a Debt Settlement Company

    Debtmerica is a fully accredited member of AFCC (The American Fair Credit Council) and has been audited to verify that we are fully compliant with all of its best practice standards. If you are thinking about working with a debt settlement company to settle your debts, there are some essential questions we feel you should ask before you sign up::

    1. Are you a member of AFCC?

    AFCC (The American Fair Credit Council) is the largest trade association serving the debt settlement industry. AFCC members voluntarily agree to comply with AFCC’s strict industry standards. Any company you choose should be an accredited member. By being accredited, the firm has been audited on-site by an independent third party verification organization, which verifies that the debt settlement firm adheres to the AFCC best practices standards needed for accreditation. Don’t settle for anything less!

    2. How long have you been in the debt settlement business and how much debt have you settled?

    Many firms out there may have flashy websites or sound professional on the phone, but you’d be surprised of their actual experience level. Many if not most, don’t even have their own marketing initiatives in place and simply buy leads from lead generation companies. In addition, certain agents you speak with may not have experience with debt settlement either and are simply professional salespeople, looking for a fast commission. If the debt settlement firm cannot provide proof of its experience, settlement history, and accreditation, you should not be working with them.

    3. Are you licensed in my state?

    There is legislation in a minority of states which places restrictions and requirements on any form of debt management. While the federal government in many ways regulates debt settlement in addition to state governments, it’s important that you as the consumer follow up with any firm you work with to find out if they are able to legally provide services in your state.

    4. What are your fees?

    Debtmerica’s programs are performance-based, which means that our clients do not pay any fees until settlements have been negotiated on their accounts. The total fees for our programs range from 20% to 24% of the enrolled debt balances that are settled. Upon each account being settled, a fee will be assessed specific to that settlement and collected from the special purpose account set up specifically to facilitate the debt settlement process.

    5. Will you be making monthly payments to my creditors?

    Debt settlement firms do not make your monthly payments to creditors for you. Rather, any payments made to creditors are a result of negotiated lump sum settlements or in rare cases, based on a pre-negotiated settlement payment plan.

    6. Who is holding my money while I’m waiting on a settlement?

    Your funds should be held at a third party account, referred to by many as a “special purpose account” which is FDIC insured. This account should always be in your name with you having ultimate control over its funds regardless of the terms of your settlement program. If the debt settlement firm tells you to save money on your own, the likelihood of graduating from your program historically has proven very minimal. Any reputable debt settlement firm endorses the special purpose account as the most effective method of client savings.

    7. When can I expect my first settlement?

    If you make your monthly payments on time and follow your program protocol correctly, you should experience your first settlement within 4-6 months. However, settlement isn’t an exact science. If you only carry a couple very large balances, then it may take longer depending on your creditors and your monthly payment. However, you should discuss your specific situation with a certified debt specialist.

    8. Can you stop my creditors from calling me?

    It is impossible to stop all creditor calls.

    9. Can I get sued?

    Yes, this is a possibility based on the motives of each individual creditor but it is based on several factors and isn’t as cut-and-dry as one would assume. Any reputable debt settlement firm will never put you into a program that lasts over 48 months. This greatly minimizes the risk as much as possible.

    10. Will this have a negative effect on my credit report?

    Yes, there will be an adverse effect on your credit report while in your debt settlement program. All debt settlement programs will have a negative impact on your credit report and you should be VERY cautious of any firm that tells you to the contrary.

    AFCC’s Top 10 Frequently Asked Questions

    AFCC (The American Fair Credit Council) wants you to understand both the potential benefits and pitfalls that may arise out of the debt settlement process and to have reasonable expectations regarding the outcome of your program. Below are the questions which AFCC has laid out on its own in its efforts to successfully guide consumers to the most favorable outcome when enrolling in a debt settlement program. We wanted to also include them for you.

    1. What is the goal of a debt settlement program?

    When you enroll into a debt settlement program, the goal you have set is to negotiate mutually agreeable settlements between you and your creditor(s) for payment of certain unsecured debt(s) described as Enrolled Debts. No specific results can be predicted or guaranteed.

    2. What are my responsibilities once I enroll in a debt settlement program?

    After saving sufficient funds, you will be responsible for controlling the fund settlements that your debt settlement company will endeavor to negotiate on your behalf. You, and only you, will be in control of all settlement funds. Under no circumstances will your debt settlement company have custody or control of the funds you set aside to fund debt settlements.

    3. How much will I be expected to save towards my debt settlements?

    The savings plan you are expected to follow will be detailed in your Client Agreement. Summaries of the total settlement amount, monthly savings, and the period needed to reach your goal will be prepared based on the goal you select. Those summaries reflect the minimum amount that your debt settlement company has estimated you will need to save to put yourself in a position to reach your goals and come up with some debt remedy solutions. Actual settlement amounts, necessary savings and the period required to reach your goal may vary based on creditors actions and other factors.

    4. Will all of my creditors and collectors negotiate with debt settlement companies?

    Most creditors and collectors negotiate with debt settlement service providers. Debt settlement companies cannot force the negotiations and cannot force creditors to accept a settlement. Debt settlement companies do not make regular monthly payments to your creditors. Your creditors may continue collection efforts on delinquent accounts while you are enrolled in a debt settlement program. Such collection efforts can include phone calls and letters to you, charging off the account, sending accounts to collection agencies or attorneys, lawsuits and even garnishments of your wages if a judgment has been obtained. Debt settlement companies should not claim that they will be able to stop these collection activities as these activities may continue while the company is making its best efforts to negotiate your debt.

    5. How long does a debt settlement program last?

    Debt settlement programs assume an effort that will continue for many months. The time needed to produce a settlement depends on a number of factors. These may include: (a) your financial hardship, (b) the age and balance of the accounts that you owe your creditors, c) the funds you have available to pay for a settlement and (d) the willingness of individual creditors to enter into debt settlement negotiations. While no guarantees can be given, generally the quicker you save money the sooner you will be in a position to reach your goals. Increased savings will provide you with the option to accept lesser discounts and will also enable you to accumulate funds to reach your debt settlement goals more quickly. However, any settlement must be acceptable to both you and your settling creditor.

    6. What do the debt settlement company’s fees cover?

    The fees paid to debt settlement companies are intended to compensate the company for its efforts and will only be refundable to the extent they have not been deemed to have been earned in the manner described in the Client Agreement. Debt settlement program fees are not being set aside or held in escrow to fund debt settlements.

    7. When does the debt settlement company communicate with my creditors?

    Communications with the creditors are handled on a case by case basis. In some instances creditors may not be contacted until several months after you enroll.

    8. What is debt settlement?

    Debt settlement companies provide consumers with a method of debt resolution known as debt settlement. Debt settlement is an aggressive method of debt management that depends on the negotiation of mutually agreeable settlements between the consumers and the creditors.

    9. Is the amount I save on each of my settlements taxable?

    When your creditor settles your debt, a savings of $600 or more off what you owed may be reported by your creditor to the IRS as Discharge of Indebtedness income. You may wish to consult your tax advisor to determine whether your individual circumstances may permit you to exclude any such Discharge of Indebtedness Income from your reportable income due to insolvency. For more information on tax ramifications to you personally you may also wish to consult a CPA or Tax Attorney and to refer to the IRS website www.irs.gov IRS Publication 908- “Bankruptcy Tax Guide” and IRS Form 982, Reduction of Tax Attributes Due to Discharge of Indebtedness available on the IRS website.

    No, debt settlement companies are not law firms and cannot provide legal advice.
  • Real Testimonials from Debtmerica Customers

    Real Testimonials from Debtmerica Customers

    What are people saying about Debtmerica?*

    *Testimonials are based on individual’s experience and individual experiences will vary depending on your specific circumstances.


    “I had many questions and made many calls to Dan throughout this process.  He always answered all of my questions in a manner that left me feeling assured and comfortable with this program.”

    Paula M.


    [Stephanie] “it’s nice to know that there’s still a company like yours out there helping people out like me. Most of all, having someone like you who has true compassion with people and knows what you are doing, is the greatest asset to a company.”

    Maria D.


    “Ron’s communications with me during this emotional time in my life have been respectful and caring as well as easy to understand and honest, I hope this will help him to earn some sort of promotion because he deserves it!”

    Julia P.


    “Not only were you [Sonia] polite and professional but answered every question I had in a timely manner. I think you are terrific and a great asset to the company, although I have to say I hope this is the last time we have to do business 🙂 Thanks again for everything you have done for us, you’re great!!!”

    Lynsey F.


    “Thank you for your assistance [Brian] – and persistence! You did a great job. I never felt pressured. In fact, your follow-up reminded me that I had an option other than bankruptcy.”

    Anna N.


    [Ann] “Thank you for your professional, friendly and informative service.  I called other companies inquiring about their programs… Your service topped all of them!”

    Debra S.


    “The guidance and understanding I have received from you has been well appreciated. I have felt as if I was communicating with an individual not a company. “I spoke with Sonia today” not “The Company called”. This type of treatment is so essential, when someone is going through a time of questioning their worth, due to the strains of daily life as they attempt to put their financial life back in order.”

    Kimberly


    “Annie, I just wanted to thank you for your help. I was at a point where I didn’t have any answers. I was seriously contemplating bankruptcy. In fact, if you and I didn’t have our conversation last night, this would be the direction I was heading. You’re company has given me hope.”

    James


    “John, I just wanted to tell you that I appreciated how nice and understanding you were thru this embarrassing issue of ours. I was so afraid that the person on the other end of the phone would make me feel worst than I do and you did just the opposite. You definitely made the process easier than I thought it would be and still left me with some pride and dignity.”

    Lou Ann


    “Thank you! I appreciate your courtesy and the swiftness of your operation. I will recommend Debtmerica to anyone who asks me for advice on finding a way out of debt.”

    Ashley


    “Letty has been kind, reliable and a joy to talk to. When she says she will call back she does and everything she said would happen did. I have already given her number out to two friends that also need help in these trying times. She is a true professional.”

    Kim

  • Top Debt Settlements

    Top Debt Settlements

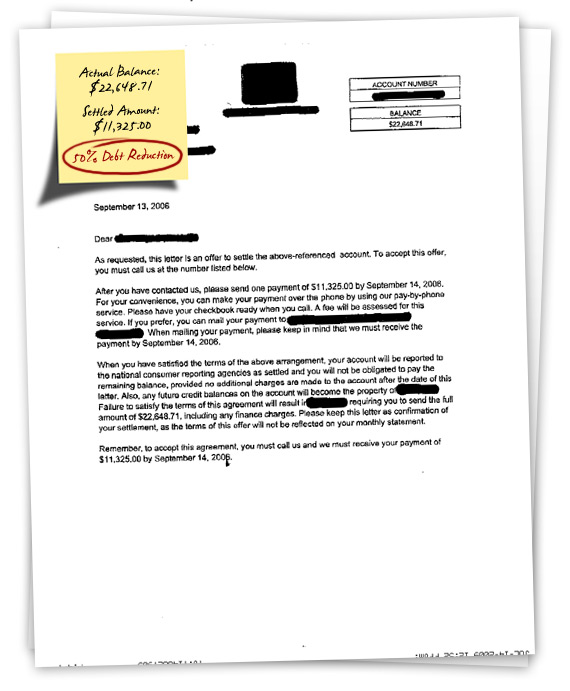
    Sample Debt Settlement Letter

    A Sample of Success

    Check out a sample debt settlement letter by clicking the thumbnail image on the right. This is just an example of what a real life settlement letter looks like. Clients who successfully complete our Debt Resolution Program can expect to get similar ones.

    Take a look at some of the top settlements we’ve listed below. These top settlements showcase how much some of our clients have saved with Debtmerica Relief!* Settlement examples are a result of creditor negotiations made by Freedom Financial Network or affiliated companies.


    Examples include top settlements achieved by our service providers and are not indicative of typical results.

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt Reduction Type of Debt
    $8,487.00 $848.71 10.00% 31.00% 69.00% CC
    $32,190.00 $9,600.00 29.82% 46.82% 53.18% CC
    $35,459.00 $11,600.00 32.71% 47.71% 52.29% CC
    $24,401.00 $6,437.08 26.38% 41.38% 58.62% CC
    $10,446.00 $2,156.96 20.65% 35.65% 64.35% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt Reduction Type of Debt
    $8,665.00 $1,124.00 12.97% 27.97% 72.03% CC
    $13,800.00 $3,200.00 23.19% 38.19% 61.81% CC
    $3,620.43 $1,175.00 32.45% 47.45% 52.55% CC
    $15,579.00 $2,157.00 13.85% 34.14% 65.86% CC
    $24,202.00 $9,368.34 38.71% 59.71% 40.29% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt Reduction Type of Debt
    $4,141.00 $881.60 21.29% 39.29% 60.71% CC
    $10,363.00 $2,792.00 26.94% 44.94% 55.06% CC
    $26,654.00 $6,664.00 25.00% 46.00% 54.00% CC
    $26,780.00 $6,234.01 23.28% 38.28% 61.72% CC
    $32,900.00 $6,132.41 18.64% 33.64% 66.36% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt Reduction Type of Debt
    $13,349.00 $3,196.00 23.94% 40.94% 59.06% CC
    $15,037.00 $3,760.00 25.00% 40.00% 60.00% CC
    $20,406.00 $4,730.90 23.18% 44.14% 55.86% CC
    $17,689.00 $5,166.00 29.20% 44.20% 55.80% CC
    $9,049.00 $2,070.00 22.88% 37.88% 62.12% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt Reduction Type of Debt
    $10,909.00 $700.00 6.42% 21.42% 78.58% CC
    $8,541.00 $1,788.00 20.93% 43.93% 56.07% CC
    $3,527.00 $839.95 23.81% 44.81% 55.19% CC
    $8,542.00 $2,435.04 28.51% 43.51% 56.49% CC
    $29,846.00 $9,197.00 30.81% 51.81% 48.19% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt Reduction Type of Debt
    $6,284.00 $1,700.00 27.05% 42.05% 57.95% CC
    $19,654.00 $4,511.76 22.95% 37.95% 62.05% CC
    $7,417.00 $1,633.23 22.02% 43.02% 56.98% CC
    $13,779.00 $212.47 1.54% 16.54% 83.46% CC
    $4,229.00 $568.00 13.43% 34.43% 65.57% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,880.00 $   800.00   5.04% 23.04% 76.96% CC
    $14,002.00 $1,571.99 11.23% 26.23% 73.77% CC
    $  5,445.00 $1,129.40 20.74% 35.74% 64.26% CC
    $21,965.00 $5,008.00 22.80% 37.80% 62.20% CC
    $20,190.00 $4,039.00 20.00% 41.00% 59.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $ 9,500.00 $   697.00   7.34% 22.34% 77.66% CC
    $51,700.00 $12,278.64 23.75% 38.75% 61.25% CC
    $41,818.00 $10,800.00 25.83% 40.83% 59.17% CC
    $ 7,795.17 $1,560.06 20.01% 41.01% 51.72% CC
    $13,368.00 $3,647.00 27.28% 48.28% 51.72% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $14,957.00 $1,530.00 10.48% 25.48% 74.52% CC
    $  5,397.00 $   917.00 16.99% 31.99% 68.01% CC
    $25,937.00 $4,528.12 17.46% 32.46% 67.54% CC
    $19,902.00 $5,206.44 26.16% 41.16% 58.84% CC
    $52,048.00 $20,000.00 38.43% 53.43% 46.57% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  1,604.00 $   167.70 10.46% 25.46% 74.54% CC
    $14,430.00 $2,317.00 16.06% 31.06% 68.94% CC
    $26,149.00 $4,656.00 17.81% 32.81% 67.19% CC
    $32,324.00 $7,297.14 22.57% 37.57% 62.43% CC
    $49,303.00 $13,074.00 26.52% 41.52% 58.48% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  1,974.00 $   228.70 11.59% 26.59% 73.41% CC
    $16,011.00 $2,732.00 17.06% 32.06% 67.94% CC
    $28,658.00 $6,075.00 21.20% 36.20% 63.80% CC
    $  6,204.00 $1,500.00 24.18% 39.18% 60.82% CC
    $52,512.00 $17,660.00 33.63% 48.63% 51.37% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $35,225.00 $5,360.00 15.22% 30.22% 69.78% CC
    $  6,776.00 $1,250.00 18.45% 33.45% 66.55% CC
    $60,700.00 $12,000.00 19.77% 34.77% 65.23% CC
    $23,600.00 $5,340.00 22.63% 37.63% 62.37% CC
    $  6,919.00 $2,170.00 31.36% 46.36% 53.64% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  2,955.00 $   300.00 10.15% 25.15% 74.85% CC
    $27,704.00 $5,381.00 19.42% 34.42% 65.58% CC
    $  8,921.00 $1,754.00 19.66% 34.66% 65.34% CC
    $17,279.00 $4,251.00 24.60% 39.60% 60.40% CC
    $49,300.00 $15,000.00 30.43% 45.43% 54.57% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,002.00 $1,524.00 10.16% 25.16% 74.84% CC
    $  6,546.00 $   759.00 11.59% 26.59% 73.41% CC
    $42,841.00 $8,168.00 19.07% 34.07% 65.93% CC
    $16,121.00 $3,438.00 21.33% 36.33% 63.67% CC
    $81,371.00 $28,415.00 34.92% 49.92% 50.08% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $20,551.81 $5,653.00 27.51% 42.51% 57.49% CC
    $11,356.66 $3,407.00 30.00% 45.00% 55.00% CC
    $  2,097.80 $   248.90 11.86% 26.86% 73.14% CC
    $  3,028.36 $   605.67 20.00% 35.00% 65.00% CC
    $  4,567.75 $1,142.00 25.00% 40.00% 60.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $22,542.24 $2,300.00 10.20% 25.20% 74.80% CC
    $12,011.82 $1,410.62 11.74% 26.74% 73.26% CC
    $  7,333.64 $1,034.00 14.10% 29.10% 70.90% CC
    $36,631.53 $5,494.73 15.00% 30.00% 70.00% CC
    $19,420.78 $8,739.35 45.00% 60.00% 40.00% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $28,848.80 $2,818.85 11.82% 26.82% 73.18% CC
    $11,674.96 $1,500.00 12.85% 27.85% 72.15% CC
    $15,484.77 $2,163.00 13.97% 28.97% 71.03% CC
    $  4,694.21 $   704.13 15.00% 30.00% 70.00% CC
    $33,446.31 $5,017.00 15.00% 30.00% 70.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,046.11 $1,505.00 10.00% 25.00% 75.00% CC
    $  7,863.13 $   786.32 10.00% 25.00% 75.00% CC
    $  5,664.34 $   566.43 10.00% 25.00% 75.00% CC
    $10,121.42 $1,013.00 10.01% 25.01% 74.99% CC
    $12,393.47 $1,240.00 10.01% 25.01% 74.99% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  2,663.95 $   267.00 10.02% 25.02% 74.98% CC
    $  3,665.95 $   407.33 11.11% 26.11% 73.89% CC
    $  9,860.66 $1,400.00 14.20% 29.20% 70.80% CC
    $15,215.41 $2,282.00 15.00% 30.00% 70.00% CC
    $18,134.64 $2,720.00 15.00% 30.00% 70.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,577.48 $1,400.00   8.99% 23.99% 76.01% CC
    $  8,367.62 $   837.00 10.00% 25.00% 75.00% CC
    $12,119.44 $1,212.00 10.00% 25.00% 75.00% CC
    $  8,607.68 $   861.00 10.00% 25.00% 75.00% CC
    $11,603.25 $1,160.63 10.00% 25.00% 75.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $26,725.01 $2,299.00   8.60% 23.60% 76.40% CC
    $24,571.24 $2,300.00   9.36% 24.36% 75.64% CC
    $10,277.41 $1,000.00   9.73% 24.73% 75.27% CC
    $42,230.30 $4,225.00 10.00% 25.00% 75.00% CC
    $  2,544.68 $   254.47 10.00% 25.00% 75.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $12,270.68 $1,140.00   9.29% 24.29% 75.71% CC
    $  5,120.00 $   512.00 10.00% 25.00% 75.00% CC
    $20,741.98 $2,074.20 10.00% 25.00% 75.00% CC
    $20,896.73 $2,100.00 10.05% 25.05% 74.95% CC
    $  8,894.16 $   936.00 10.52% 25.52% 74.48% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $11,838.44 $   896.00   7.57% 22.57% 77.43% CC
    $19,927.00 $1,521.00   7.63% 22.63% 77.37% CC
    $20,387.23 $1,779.00   8.73% 23.73% 76.27% CC
    $  6,933.99 $   620.00   8.94% 23.94% 76.06% CC
    $21,616.65 $2,000.00   9.25% 24.25% 75.75% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $11,685.96 $   744.00   6.37% 21.37% 78.63% CC
    $17,402.25 $1,659.00   9.53% 24.53% 75.47% CC
    $  6,627.29 $   661.00   9.97% 24.97% 75.03% CC
    $  9,801.25 $   980.00 10.00% 25.00% 75.00% CC
    $12,292.03 $1,230.00 10.01% 25.01% 74.99% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $20,433.19 $1,170.00   5.73% 20.73% 79.27% CC
    $14,927.25 $1,045.00   7.00% 22.00% 78.00% CC
    $  7,808.64 $   650.00   8.32% 23.32% 76.68% CC
    $20,264.30 $2,027.00 10.00% 25.00% 75.00% CC
    $  5,651.69 $   565.17 10.00% 25.00% 75.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  2,239.73 $   169.40   7.56% 22.56% 77.44% CC
    $  2,267.39 $   182.55   8.05% 23.05% 76.95% CC
    $19,071.88 $1,560.00   8.18% 23.18% 76.82% line
    $  5,416.38 $   450.00   8.31% 23.31% 76.69% CC
    $  6,224.07 $   591.00   9.50% 24.50% 75.50% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $40,831.79 $3,273.00   8.02% 23.02% 76.98% CC
    $  1,296.05 $   126.91   9.79% 24.79% 75.21% CC
    $26,868.72 $2,685.00   9.99% 24.99% 75.01% CC
    $12,959.85 $1,296.00 10.00% 25.00% 75.00% CC
    $  1,398.99 $   139.90 10.00% 25.00% 75.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $14,157.19 $1,400.00   9.89% 24.89% 75.11% CC
    $11,233.82 $1,124.00 10.01% 25.01% 74.99% CC
    $12,258.10 $1,300.00 10.61% 25.61% 74.39% CC
    $20,499.04 $2,200.00 10.73% 25.73% 74.27% CC
    $11,499.22 $2,299.84 20.00% 35.00% 65.00% line

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  6,584.28 $   622.20   9.45% 24.45% 75.55% CC
    $19,605.26 $2,000.00 10.20% 25.20% 74.80% CC
    $11,294.77 $1,309.00 11.59% 26.59% 73.41% CC
    $  5,567.88 $   724.00 13.00% 28.00% 72.00% CC
    $  7,545.52 $1,100.00 14.58% 29.58% 70.42% line

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $14,212.26 $1,525.00 10.73% 25.73% 74.27% CC
    $  8,837.00 $   972.00 11.00% 26.00% 74.00% CC
    $  9,640.54 $1,100.00 11.41% 26.41% 73.59% CC
    $21,693.83 $2,500.00 11.52% 26.52% 73.48% CC
    $21,703.07 $2,600.00 11.98% 26.98% 73.02% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $11,613.68 $1,161.37 10.00% 25.00% 75.00% CC
    $10,997.00 $1,099.78 10.00% 25.00% 75.00% CC
    $11,960.18 $1,200.00 10.03% 25.03% 74.97% CC
    $48,412.70 $4,900.00 10.12% 25.12% 74.88% CC
    $13,575.83 $1,400.00 10.31% 25.31% 74.69% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $20,627.60 $1,900.00  9.21% 24.21% 75.79% CC
    $33,191.00 $3,319.14 10.00% 25.00% 75.00% CC
    $  4,835.45 $   483.55 10.00% 25.00% 75.00% CC
    $  3,121.00 $   312.10 10.00% 25.00% 75.00% CC
    $21,275.09 $2,200.00 10.34% 25.34% 74.66% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  1,570.16 $   170.30 10.85% 25.85% 74.15% CC
    $62,977.05 $7,000.00 11.12% 26.12% 73.88% line
    $31,365.82 $3,500.00 11.16% 26.16% 73.84% CC
    $49,313.99 $6,000.00 12.17% 27.17% 72.83% CC
    $40,916.96 $5,022.40 12.27% 27.27% 72.73% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $11,343.86 $1,134.38 10.00% 25.00% 75.00% CC
    $12,473.13 $1,248.00 10.01% 25.01% 74.99% CC
    $13,747.00 $1,445.00 10.51% 25.51% 74.49% CC
    $11,937.07 $1,320.00 11.06% 26.06% 73.94% CC
    $17,652.20 $2,000.00 11.33% 26.33% 73.67% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $20,657.02 $2,000.00   9.68% 24.68% 75.32% CC
    $13,631.64 $1,363.17 10.00% 25.00% 75.00% CC
    $16,293.15 $1,650.00 10.13% 25.13% 74.87% CC
    $14,747.50 $1,505.00 10.21% 25.21% 74.79% CC
    $  5,498.53 $   980.00 17.82% 32.82% 67.18% line

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,981.76 $1,500.00   9.39% 24.39% 75.61% CC
    $12,862.07 $1,287.00 10.01% 25.01% 74.99% CC
    $  6,270.04 $   636.00 10.14% 25.14% 74.86% CC
    $11,730.87 $1,200.00 10.23% 25.23% 74.77% CC
    $23,016.74 $3,500.00 15.21% 30.21% 69.79% line

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $11,718.41 $1,171.84 10.00% 25.00% 75.00% CC
    $27,750.35 $2,775.00 10.00% 25.00% 75.00% CC
    $13,840.68 $1,500.00 10.84% 25.84% 74.16% CC
    $10,793.23 $1,620.00 15.01% 30.01% 69.99% CC
    $12,196.98 $2,000.00 15.21% 30.21% 69.79% line

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $19,621.87 $2,096.00 10.68% 25.68% 74.32% CC
    $26,871.89 $3,350.00 12.47% 27.47% 72.53% CC
    $15,149.11 $2,160.00 14.26% 29.26% 70.74% CC
    $16,729.54 $2,500.00 14.94% 29.94% 70.06% line
    $14,824.08 $2,223.61 15.00% 30.00% 70.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $19,440.58 $1,549.00   7.97% 22.97% 77.03% CC
    $19,753.05 $2,000.00 10.13% 25.13% 74.87% CC
    $16,349.99 $1,700.00 10.40% 25.40% 74.60% CC
    $13,880.57 $1,500.00 10.81% 25.81% 74.19% CC
    $12,081.91 $1,700.00 14.07% 29.07% 70.93% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  9,320.60 $1,145.00 12.28% 27.28% 72.72% CC
    $38,051.76 $5,024.00 13.20% 28.20% 71.80% CC
    $11,164.19 $1,550.00 13.88% 28.88% 71.12% CC
    $  2,810.86 $   400.00 14.23% 29.23% 70.77% CC
    $13,184.99 $1,980.00 15.02% 30.02% 69.98% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $23,287.04 $2,500.00 10.74% 25.74% 74.26% CC
    $  5,362.63 $   600.00 11.19% 26.19% 73.81% Line
    $  6,725.00 $   800.00 11.90% 26.90% 73.10% CC
    $  8,652.36 $1,263.00 14.60% 29.60% 70.40% CC
    $     688.26 $   103.00 14.97% 29.97% 70.03% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  3,103.89 $   220.00   7.09% 22.09% 77.91% CC
    $  4,868.25 $   609.00 12.51% 27.51% 72.49% CC
    $13,570.00 $1,715.00 12.64% 27.64% 72.36% CC
    $  1,898.30 $   261.00 13.75% 28.75% 71.25% loan
    $10,668.35 $1,620.00 15.16% 30.16% 69.84% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $11,535.59 $1,200.00 10.40% 25.40% 74.60% CC
    $18,357.23 $2,100.00 11.44% 26.44% 73.56% loan
    $  5,398.12 $   810.00 15.01% 30.01% 69.99% loan
    $13,316.31 $2,000.00 15.02% 30.02% 69.98% CC
    $  4,571.50 $   690.00 15.09% 30.09% 69.91% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $29,290.82 $3,000.00 10.24% 25.24% 74.76% CC
    $12,192.02 $1,584.00 12.99% 27.99% 72.01% CC
    $23,448.43 $3,278.00 13.98% 28.98% 71.02% CC
    $15,272.18 $2,300.00 15.06% 30.06% 69.94% CC
    $19,072.74 $2,900.00 15.20% 30.20% 69.80% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $27,391.65 $4,955.00 18.09% 33.09% 66.91% CC
    $17,070.80 $5,124.24 30.00% 45.00% 55.00% CC
    $26,589.31 $6,700.00 25.20% 40.20% 59.80% loan
    $11,943.12 $2,983.00 24.98% 39.98% 60.02% CC
    $11,131.88 $2,200.00 19.76% 34.76% 65.24% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  8,822.43 $1,411.00 15.99% 30.99% 69.01% line
    $18,950.34 $3,800.00 20.05% 35.05% 64.95% CC
    $12,903.30 $2,700.00 20.92% 35.92% 64.08% CC
    $  1,563.90 $   350.00 22.38% 37.38% 62.62% CC
    $  5,770.41 $1,442.50 25.00% 40.00% 60.00% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $20,064.68 $3,010.00 15.00% 30.00% 70.00% CC
    $  6,731.17 $1,010.00 15.00% 30.00% 70.00% loan
    $13,113.60 $1,968.00 15.01% 30.01% 69.99% CC
    $  2,504.95 $   500.00 19.96% 34.96% 65.04% loan
    $19,660.98 $3,933.00 20.00% 35.00% 65.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $35,164.18 $4,216.00 11.99% 26.99% 73.01% CC
    $24,757.06 $4,000.00 16.16% 31.16% 68.84% CC
    $  2,778.11 $   474.35 17.07% 32.07% 67.93% CC
    $  6,962.11 $1,338.42 20.00% 35.00% 65.00% line
    $  7,673.29 $1,534.66 20.00% 35.00% 65.00% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,000.00 $2,200.00 14.67% 29.67% 70.33% CC
    $  6,675.95 $1,001.00 15.00% 30.00% 70.00% line
    $14,485.54 $2,200.00 15.19% 30.19% 69.81% CC
    $25,749.40 $4,700.00 18.25% 33.25% 66.75% CC
    $50,203.38 $9,801.00 19.52% 34.52% 65.48% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $ 32,346.91 $2,320.00   7.17% 22.17% 77.83% CC
    $18,863.37 $3,000.00 15.90% 30.90% 69.10% line
    $12,199.60 $1,830.00 15.00% 30.00% 70.00% CC
    $  2,099.13 $   418.00 19.90% 34.90% 65.10% loan
    $  1,846.53 $   370.00 20.04% 35.04% 64.96% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  1,010.05 $   101.01 10.00% 25.00% 75.00% CC
    $10,242.63 $1,515.00 14.79% 29.79% 70.21% CC
    $50,005.39 $7,501.00 15.00% 30.00% 70.00% CC
    $24,422.01 $3,665.00 15.01% 30.01% 69.99% loan
    $18,353.56 $5,500.00 29.97% 44.97% 55.03% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  7,175.96 $1,435.19 20.00% 35.00% 65.00% CC
    $  2,612.85 $   655.00 25.07% 40.07% 59.93% Loan
    $18,504.40 $4,000.00 21.62% 36.62% 63.38% CC
    $28,986.74 $8,610.00 29.70% 44.70% 55.30% CC
    $11,274.29 $3,385.29 30.03% 45.03% 54.97% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,912.36 $2,400.00 15.08% 30.08% 69.92% CC
    $15,610.26 $3,000.00 19.22% 34.22% 65.78% CC
    $  8,204.14 $1,641.00 20.00% 35.00% 65.00% Loan
    $  8,267.84 $2,480.00 30.00% 45.00% 55.00% CC
    $47,274.37 $7,564.00 16.00% 31.00% 69.00% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $  7,243.16 $   869.17 12.00% 27.00% 73.00% CC
    $  9,810.70 $1,200.00 12.23% 27.23% 72.77% CC
    $  6,134.78 $1,230.00 20.05% 35.05% 64.95% Loan
    $20,730.85 $4,270.00 20.26% 35.26% 64.74% CC
    $26,636.96 $5,400.00 20.27% 35.27% 64.73% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,619.62 $2,492.95 15.96% 30.96% 69.04% CC
    $  3,853.37 $   771.00 20.01% 35.01% 64.99% Loan
    $17,417.37 $3,600.00 20.67% 35.67% 64.33% CC
    $     647.00 $   150.00 23.18% 38.18% 61.82% Loan
    $  4,300.62 $1,502.00 34.93% 49.93% 50.07% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $12,010.27 $2,041.74 17.00% 32.00% 68.00% CC
    $12,567.31 $3,180.00 25.30% 40.30% 59.70% Loan
    $12,872.26 $2,600.00 20.20% 35.20% 64.80% CC
    $11,312.02 $1,700.00 15.03% 30.03% 69.97% CC
    $  9,296.38 $2,500.00 26.89% 41.89% 58.11% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $18,009.61 $2,701.00 15.00% 30.00% 70.00% CC
    $  1,368.00 $   220.00 16.08% 31.08% 68.92% Retail
    $10,976.95 $2,100.00 19.13% 34.13% 65.87% CC
    $18,019.47 $5,405.84 25.00% 40.00% 60.00% Line
    $  8,234.41 $2,058.60 30.00% 45.00% 55.00% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $6,426.01 $1,200.00 18.67% 33.67% 66.33% CC
    $   769.00 $       0.00   0.00% 15.00% 85.00% Medical
    $5,670.45 $1,417.61 25.00% 40.00% 60.00% CC
    $2,582.48 $   646.00 25.01% 40.01% 59.99% CC
    $4,043.13 $1,200.00 29.68% 44.68% 55.32% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $15,231.45 $4,569.44 30.00% 45.00% 55.00% CC
    $  9,964.00 $1,940.80 19.48% 34.48% 65.52% line
    $  5,211.00 $1,175.32 22.55% 37.55% 62.45% CC
    $14,776.69 $3,400.00 23.01% 38.01% 61.99% CC
    $  1,392.74 $   418.00 30.01% 45.01% 54.99% Furniture

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $4,435.33 $1,000.00 22.55% 37.55% 62.45% Loan
    $4,445.20 $779.00 17.52% 32.52% 67.48% CC
    $11,095.86 $3,328.00 29.99% 44.99% 55.01% CC
    $10,832.62 $4,000.00 36.93% 51.93% 48.07% Line
    $14,261.24 $5,704.50 40.00% 55.00% 45.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $12,772.85 $1,916.00 15.00% 30.00% 70.00% CC
    $14,642.65 $5,200.00 35.51% 50.51% 49.49% CC
    $15,703.15 $5,610.00 35.73% 50.73% 49.27% CC
    $10,218.97 $3,900.00 38.16% 53.16% 46.84% CC
    $13,240.00 $5,300.00 40.03% 55.03% 44.97% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $2,285.44 $500.00 21.88% 36.88% 63.12% loan
    $5,493.45 $1,373.26 25.00% 40.00% 60.00% loan
    $1,550.68 $400.00 25.80% 40.80% 59.20% loan
    $6,421.40 $1,926.42 30.00% 45.00% 55.00% CC
    $8,503.69 $2,320.00 27.28% 42.28% 57.72% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $12,102.04 $2,420.41 20.00% 35.00% 65.00% CC
    $4,177.00 $1,000.00 23.94% 38.94% 61.06% CC
    $13,800.60 $3,450.15 25.00% 40.00% 60.00% CC
    $4,881.52 $1,500.00 30.73% 45.73% 54.27% loan
    $8,418.23 $3,480.00 41.34% 56.34% 43.66% loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $17,714.82 $2,125.77 12.00% 27.00% 73.00% CC
    $10,203.08 $1,555.00 15.24% 30.24% 69.76% CC
    $3,453.75 $690.75 20.00% 35.00% 65.00% CC
    $40,442.32 $10,062.34 24.88% 39.88% 60.12% CC
    $5,653.91 $1,500.00 26.53% 41.53% 58.47% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $4,417.57 $441.76 10.00% 25.00% 75.00% CC
    $18,746.22 $3,500.00 18.67% 33.67% 66.33% CC
    $21,283.67 $4,245.00 19.94% 34.94% 65.06% CC
    $2,237.00 $478.21 21.38% 36.38% 63.62% CC
    $9,241.41 $2,306.00 24.95% 39.95% 60.05% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $18,337.94 $3,880.00 21.16% 36.16% 63.84% CC
    $11,450.53 $4,000.00 34.93% 49.93% 50.07% loan
    $5,499.00 $1,600.00 29.10% 44.10% 55.90% CC
    $23,007.47 $8,000.00 34.77% 49.77% 50.23% CC
    $3,400.62 $950.00 27.94% 42.94% 57.06% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $9,393.00 $1,100.00 11.71% 26.71% 73.29% CC
    $15,318.19 $3,829.55 25.00% 40.00% 60.00% CC
    $11,201.70 $3,060.00 27.32% 42.32% 57.68% loan
    $2,495.85 $718.54 28.79% 43.79% 56.21% CC
    $6,039.61 $1,810.00 29.97% 44.97% 55.03% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $1,986.64 $512.45 25.79% 40.79% 59.21% CC
    $2,424.73 $700.00 28.87% 43.87% 56.13% CC
    $5,237.08 $1,571.00 30.00% 45.00% 55.00% CC
    $6,400.48 $1,970.00 30.78% 45.78% 54.22% CC
    $2,024.47 $700.00 34.58% 49.58% 50.42% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $7,677.14 $1,535.43 20.00% 35.00% 65.00% CC
    $4,059.33 $811.87 20.00% 35.00% 65.00% CC
    $11,317.33 $2,264.00 20.00% 35.00% 65.00% CC
    $2,679.41 $669.95 25.00% 40.00% 60.00% CC
    $5,578.30 $1,400.00 25.10% 40.10% 59.90% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $22,462.60 $0.00 0.00% 15.00% 85.00% CC
    $15,029.57 $2,650.00 17.63% 32.63% 67.37% CC
    $2,168.00 $500.00 23.06% 38.06% 61.94% CC
    $6,060.82 $1,400.00 23.10% 38.10% 61.90% CC
    $19,281.00 $5,000.00 25.93% 40.93% 59.07% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $6,171.64 $862.00 13.97% 28.97% 71.03% CC
    $15,613.50 $3,112.00 19.93% 34.93% 65.07% CC
    $10,648.60 $3,000.00 28.17% 43.17% 56.83% CC
    $1,749.00 $509.00 29.10% 44.10% 55.90% Jewelry
    $20,248.26 $6,000.00 29.63% 44.63% 55.37% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $2,550.90 $700.00 27.44% 42.44% 57.56% CC
    $3,570.15 $1,071.04 30.00% 45.00% 55.00% CC
    $1,061.33 $319.00 30.06% 45.06% 54.94% CC
    $6,321.72 $2,000.00 31.64% 46.64% 53.36% CC
    $1,876.34 $650.00 34.64% 49.64% 50.36% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $2,627.12 $600.00 22.84% 37.84% 62.16% Loan
    $5,295.12 $1,323.73 25.00% 40.00% 60.00% CC
    $4,786.74 $1,300.00 27.16% 42.16% 57.84% CC
    $10,998.99 $2,999.00 27.27% 42.27% 57.73% CC
    $7,054.79 $2,000.00 28.35% 43.35% 56.65% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $8,252.66 $1,300.00 15.75% 30.75% 69.25% CC
    $11,272.20 $2,820.00 25.02% 40.02% 59.98% Loan
    $11,761.94 $3,500.00 29.76% 44.76% 55.24% CC
    $9,935.88 $3,200.00 32.21% 47.21% 52.79% CC
    $18,960.03 $6,636.00 35.00% 50.00% 50.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $2,454.98 $653.00 26.60% 41.60% 58.40% Medical
    $1,501.02 $427.85 28.50% 43.50% 56.50% Retail CC
    $3,115.02 $934.50 30.00% 45.00% 55.00% CC
    $6,226.54 $1,868.00 30.00% 45.00% 55.00% CC
    $8,756.00 $2,800.00 31.98% 46.98% 53.02% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $19,093.10 $2,750.00 14.40% 29.40% 70.60% CC
    $8,972.99 $1,500.00 16.72% 31.72% 68.28% CC
    $6,036.67 $1,155.00 19.13% 34.13% 65.87% CC
    $4,582.01 $1,000.00 21.82% 36.82% 63.18% Loan
    $17,625.00 $4,450.00 25.25% 40.25% 59.75% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $20,116.55 $4,600.00 22.87% 37.87% 62.13% CC
    $5,974.51 $1,400.00 23.43% 38.43% 61.57% CC
    $12,191.00 $1,400.00 24.00% 39.00% 61.00% CC
    $14,639.94 $4,000.00 27.32% 42.32% 57.68% Loan
    $13,510.17 $3,974.00 29.41% 44.41% 55.59% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $4,174.54 $800.00 19.16% 34.16% 65.84% CC
    $5,843.00 $1,168.00 19.99% 34.99% 65.01% Loan
    $4,987.20 $1,175.00 23.56% 38.56% 61.44% CC
    $14,349.00 $4,000.00 27.88% 42.88% 57.12% CC
    $18,011.26 $5,100.00 28.32% 43.32% 56.68% CC
    $23,546.25 $7,068.00 30.02% 45.02% 54.98% Loan

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $13,049.82 $3,000.00 22.99% 37.99% 62.01% CC
    $11,409.18 $2,800.00 24.54% 39.54% 60.46% CC
    $4,972.88 $1,229.00 24.71% 39.71% 60.29% CC
    $6,459.48 $1,678.00 25.98% 40.98% 59.02% CC
    $12,351.30 $3,500.00 28.34% 43.34% 56.66% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $3,742.77 $935.00 24.98% 39.98% 60.02% CC
    $7,906.09 $2,000.00 25.30% 40.30% 59.70% Loan
    $8,495.71 $2,200.00 25.90% 40.90% 59.10% CC
    $13,265.17 $3,582.00 27.00% 42.00% 58.00% CC
    $11,850.00 $3,200.00 27.00% 42.00% 58.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $5,095.19 $1,018.05 19.98% 34.98% 65.02% CC
    $14,931.50 $3,450.00 23.11% 38.11% 61.89% CC
    $13,819.18 $3,454.00 24.99% 39.99% 60.01% Loan
    $9,419.00 $2,354.75 25.00% 40.00% 60.00% Loan
    $20,176.97 $5,450.00 27.01% 42.01% 57.99% CC
     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $3,116.00 $600.00 19.26% 34.26% 65.74% CC
    $6,026.85 $1,386.18 23.00% 38.00% 62.00% CC
    $7,947.96 $2,100.00 26.42% 41.42% 58.58% Loan
    $14,885.51 $4,470.00 30.03% 45.03% 54.97% CC
    $14,096.56 $4,934.00 35.00% 50.00% 50.00% CC

     Enrolled Debt Settlement Amount Percentage Paid by Consumer Percentage Paid with Fee Percentage Debt
    Reduction
    Type of Debt
    $3,637.73 $700.00 19.26% 34.26% 65.74% CC
    $3,256.89 $762.00 23.40% 38.40% 61.60% Line
    $3,351.89 $854.00 25.48% 40.48% 59.52% CC
    $4,434.45 $1,200.00 27.06% 42.06% 57.94% CC
    $10,810.61 $3,243.18 30.00% 45.00% 55.00% CC

    “*Settlements shown are examples of past performance, which are not intended to be a guarantee of future settlement results. Results will vary depending on one’s ability to save sufficient funds, actual creditors of an individual and creditor negotiations. “

  • Debt Relief Programs and Options

    Debt Relief Programs and Options

    There are many options when it comes to addressing your debt problems. Debtmerica believes it provides better Alternatives to Consumer Credit Counseling, Bankruptcy or Debt Consolidation Loans.

    Below are summaries of the various alternatives available to you so that you can make an informed and well-educated decision based on your own individual situation.

    Assuming you are able to make all the monthly program payments, Debtmerica can offer Debt Resolution Programs that may help you resolve your debt in as little as 24-48 months without paying any fees until a successful resolution of a debt occurs. If you are experiencing a financial or personal hardship that is preventing you from paying your bills, the five most generally accepted debt relief options you have are:

    1. Bankruptcy.

    While bankruptcy is a legitimate route to get out of debt, it can negatively affect your credit for as long as 10 years and can be a very unpleasant experience emotionally. You shouldn’t consider bankruptcy as a simple “quick fix” to all of your financial problems, but rather as one of the many available solutions you may have given your individual situation. As of October 2005, congressional legislation made filing for bankruptcy more difficult and burdensome. A Chapter 13 bankruptcy could result in higher monthly payments and may last longer than an alternative debt resolution program. If you have questions about bankruptcy or are considering it as an option, we advise you to speak directly to an experienced bankruptcy attorney licensed in your state.

    2. Consumer Credit Counseling (CCC).

    A Consumer credit counseling program is a method of debt relief for those who are unable to make minimum payments and undergoing financial difficulties. However, CCC programs could take up to 6 years or longer to complete and your debt is not reduced when compared to a debt resolution program. You may still have to pay back 100% of the debt you owe plus interest. In addition, if you miss just one monthly payment, you could be dropped from the program altogether. Consumer Credit Counseling Services, on average, have very high rates of client cancellation, which does not bode well for their delivery of a successful debt management program. (see below for more information on CCCs). With that being said, a CCC program may be a viable option for those with under $10,000 in unsecured debt, are able to afford higher monthly payment obligations, and are well disciplined to remain in the program.

    3. Debt Consolidation Loan.

    This option may work financially if you have at least an above average or good credit rating and considerable equity in your home. If you have a very large debt balance and have been late on just one monthly payment, it is likely that your credit may be impaired. Also, with this option, you do not reduce or settle your debt to a lower amount than the original balance; you are only transforming it from unsecured debt to secured debt. While a debt consolidation loan coupled with a debt resolution program provides a very powerful solution, remember that debt consolidation alone does not reduce or settle your debt; it only shifts your debt from one place to another.

    4. Continue minimum monthly payments to credit card companies.

    Many people struggle to make their minimum monthly payments and this option could take over 30 years to pay back the debt you owe, costs thousands of dollars in interest alone, and could require you to potentially pay back over three-times what you now owe on these balances. This may be the least timely, most costly, and most economically disadvantageous way to get out of your unsecured debt (see below for more information). Keeping high balances on your credit cards may affect your credit in a negative way and could make it more difficult to obtain any other type of loan.

    5. THE DEBT RESOLUTION PROGRAM

    Debt resolution is an aggressive method that allows the clients who make all their monthly program payments to settle their debt for less than the original balances owed in as little as 24-48 months. Debt resolution programs are custom-tailored to provide you with just one low monthly program payment. We feel this option could be one of the fastest ways for you to resolve your unsecured debt while we work hard to minimize your stress burden.

    Programs offered by Debtmerica are performance based, which means we do not receive any fees until a settlement has been reached. Debtmerica offers programs that either charge fees as a percentage of savings or as a total percentage of enrolled debt balances. Regardless of which program you enter, you can expect the total fees of the program to range from 20% to 24% of the enrolled debt amount by the time you complete the program.

    If you are considering all of your debt relief options, and want to get out of debt, complete our easy and hassle-free 30 Second Savings Quote to see if a debt settlement program is the best option for you.

    The projection assumes the following:

    For example, if you owe $30,000 in credit card debt it may take you the following amount of time to resolve your debt

    Avoid Bankruptcy

    Your actual results will vary depending on a variety of factors, including your current balances, how much you can afford to save per month, and the amount that your creditors are willing to settle for. We make no guarantee that your debts will be lowered by a specific amount of percentage or that you will be resolve debt within a specified time period.

    Debt Consolidation Loan

    To be approved, you must have the ability to repay a larger home loan and also have an acceptable credit rating. Even if you do qualify, without debt settlement combined, your situation could likely get worse. Rather than helping you to reduce your debt through debt settlement, a consolidation loan may increase your debt burden. Here are some more facts that you may want to know about debt consolidation loans:

    • You must qualify, which may be difficult given the recent mortgage reforms.
    • It requires ownership of a home with considerable equity
    • Closing costs are usually required upon closing or built into the interest rate
    • Missing payments could cause you to lose your home
    • You would pay back the entire balance of your credit cards, plus interest
    • Payback could be 10-30 years or more depending on debt balance, type of loan, and your ability to pay
    • You are paying off unsecured debts in favor of a new secured debt
    • The debt consolidation loan reduces the equity available in your property for future use

    Continue to Make the Minimum Payments or Don’t Pay Anything at All

    • You could pay almost 50% of your original balance to your creditor in interest costs alone over the first 36 months. Your principal balance may barely be touched
    • If your credit card interest rate is 25% or higher, it may be almost impossible to pay off your debt by making the minimum payments
    • With a high credit card interest rate, it would most likely take you over 20 years to become debt free – and that’s if your balances don’t increase
    • Until you pay off high balance debts, your ability to be extended credit becomes substantially more difficult.

    If you have already stopped making payments to your credit cards or other creditors, you are negatively affecting your credit rating without reducing, settling or managing your debt successfully.

    To see if you qualify for debt settlement, please fill out our 30 second savings quote form for a free, no cost or obligation consultation.

  • Thank You

    Thank You

    Thank you for your interest in Debtmerica Relief

    You are one step closer to becoming Debt-Free. Your Debt Consultant will be calling you shortly with a no cost or obligation consultation. If you would like to speak to someone immediately, please call us at: (800) 470-8155

  • All About Debtmerica

    All About Debtmerica

    The Debtmerica Relief team has had one vision since inception – to help Americans nationwide attain financial independence.

    image

    As we all know, debt and financial difficulties can create great personal difficulties, stress, depression, and anxiety. It’s not a very rewarding experience to be buried in debt. Debtmerica is a consumer debt reduction service that uses negotiated debt settlement to work towards aggressively reducing your unsecured debt, letting you move on with your life.

    Our Mission

    Our mission at Debtmerica is to eliminate your financial strain so that you may get back on the right track to true financial freedom and personal fulfillment. Within our network we are able to lower your unsecured debt balances, provide one low monthly program payment, offer a great alternative to bankruptcy or simply provide you with sound, knowledgeable advice. We are here to help!

    Our History

    The founders of Debtmerica first met over 12 years ago while at the Wharton Business School at the University of Pennsylvania. It is there that they quickly realized the overwhelming burden that unmanageable debt can place on Americans from every walk of life. After spending several years working with the consumer finance sector, they determined that merely consolidating high amounts of unsecured debt into secured debt via a debt consolidation loan didn’t solve the fundamental problem – too much debt to begin with! A better solution would be to not only reduce monthly payments, but in addition, to actually lower the debt balances themselves. Upon further research, they also determined that Consumer Credit Counseling – sponsored by the credit card companies themselves – typically only reduced a consumer’s annual percentage rate (APR), but did nothing to actually reduce the unsecured debt balances.

    How Debt Settlement Works

    Once you enroll in the program, our first priority is to minimize creditor harassment. With our lasting relationships with our service providers and their direct access to creditors, the debt resolution programs are able to reduce your total unsecured debt amount while providing just one low monthly program payment. This monthly payment amount is frequently as low as half as much as your current combined monthly payments to the same creditors. Our underwriting process is highly effective with the main goal to help you experience a lasting benefit to your financial well being.

    Our knowledgeable, friendly, and experienced Debt Consultants at Debtmerica will discuss with you the benefits and qualification process of our Debt Resolution Programs, and then will propose an affordable monthly program payment that will fit within your budget. We feel our program is simply the best way to become debt-free without declaring bankruptcy and without consumer credit counseling.

    Our Success

    Through our service providers, we have experienced unprecedented success at helping our clients attain financial independence. Our success comes as a result of our commitment to excellence. Debtmerica is an accredited member of TASC (The Association of Settlement Companies) and our Debt Consultants are required to attain certification from IAPDA (the International Association of Professional Debt Arbitrators). This level of professionalism was a major factor in Debtmerica becoming an Inc. 500 Fastest Growing Company for 2009 and 2010. We were also honored by the Orange County Business Journal for ranking 4th “Best Places to Work in Orange County” and #3 “Fastest Growing Private Company”. At Debtmerica, we’re proud of our achievements and honors – they represent our commitment to Debtmerica’s vision.

    Our goal is to have no repeat customers!

    While we appreciate the referrals of friends and family, we want all of our graduates to be on a solid path to financial freedom. If you have any questions or concerns send us a note on our contact us page.

    Call us Toll-Free at 800-470-8155 for a free, no cost or obligation consultation.

  • Lorem Ipsum

    Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry’s standard dummy text ever since the 1500s, when an unknown printer took a galley of type and scrambled it to make a type specimen book. It has survived not only five centuries, but also the leap into electronic typesetting, remaining essentially unchanged. It was popularised in the 1960s with the release of Letraset sheets containing Lorem Ipsum passages, and more recently with desktop publishing software like Aldus PageMaker including versions of Lorem Ipsum.

    Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry’s standard dummy text ever since the 1500s, when an unknown printer took a galley of type and scrambled it to make a type specimen book. It has survived not only five centuries, but also the leap into electronic typesetting, remaining essentially unchanged. It was popularised in the 1960s with the release of Letraset sheets containing Lorem Ipsum passages, and more recently with desktop publishing software like Aldus PageMaker including versions of Lorem Ipsum.

  • 404

    404: Not Found

    Sorry, but the content you requested could not be found

    404 – Component not found

    You may not be able to visit this page because of:

    1. an out-of-date bookmark/favourite
    2. a search engine that has an out-of-date listing for this site
    3. a mistyped address
    4. you have no access to this page
    5. The requested resource was not found.
    6. An error has occurred while processing your request.

    Please try one of the following pages:

    If difficulties persist, please contact the System Administrator of this site.

    Component not found